SPX Pre-NY Open map — Wednesday 28 October 2026
Anchored at 7725 today, the next three days turn choppy between 7820 and 7700.
Anchored at 7725 today, the next three days turn choppy between 7820 and 7700
Prior close 7,722.60 (SPX, Yahoo, 27 Oct) · VIX 17.43 (Yahoo, 08:16 ET) · Indicated level 7,738.10 (SPX perpetual, Hyperliquid, not the index; +15.50 pts vs the prior close) · Options snapshot 08:30 ET
Read this first. This describes overnight positioning at the 08:30 ET snapshot. It is a description, not a forecast. The actual open can change it radically, and often does: new positioning arrives at 09:30 ET and can reverse the picture.
How to read it. Steadying means net gamma is positive and market-maker hedging tends to lean against a move; amplifying means it is negative and hedging tends to follow a move. The anchor is the strike within 100 points of the print with the largest positive net, the weak spot the one with the largest negative net.
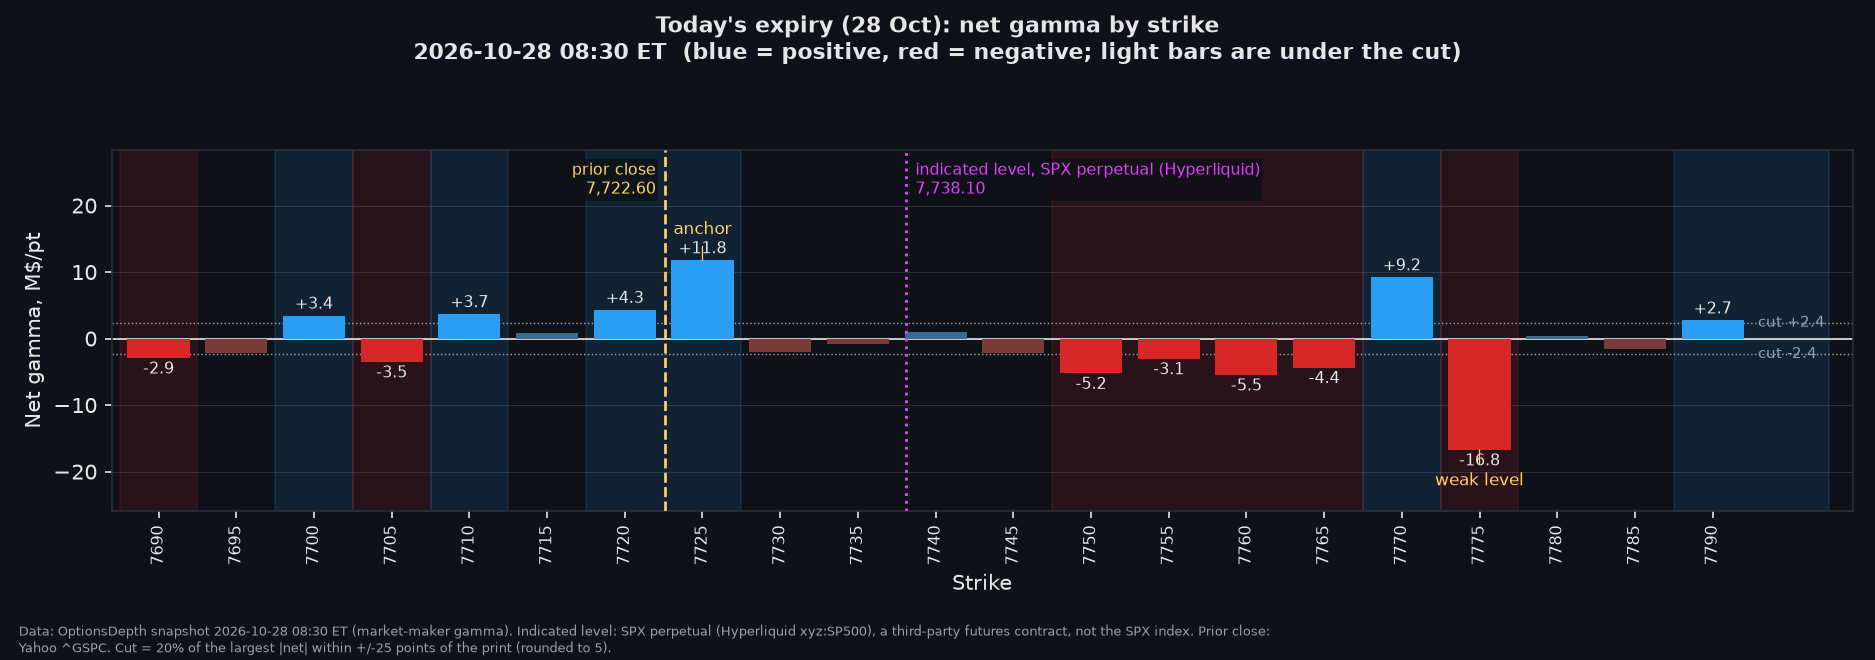
Today (28 Oct expiry)
Steadying, net +1.4 M$/pt. That is higher than 4 of the last 20 sessions at this hour.
Since the 27 Oct close it went from +4.9 to +1.4 (−3.5); the 27 Oct 20:00 to 28 Oct 04:00 ET window is where the new positioning formed.
The anchor is 7725 (+11.8), the strongest positive strike; the weak spot is 7775 (−16.8), the largest negative.
One-day expected move: ±84.8 points, a box of 7,637.8 to 7,807.4 (prior close × VIX ÷ 100 × √(1/252)).
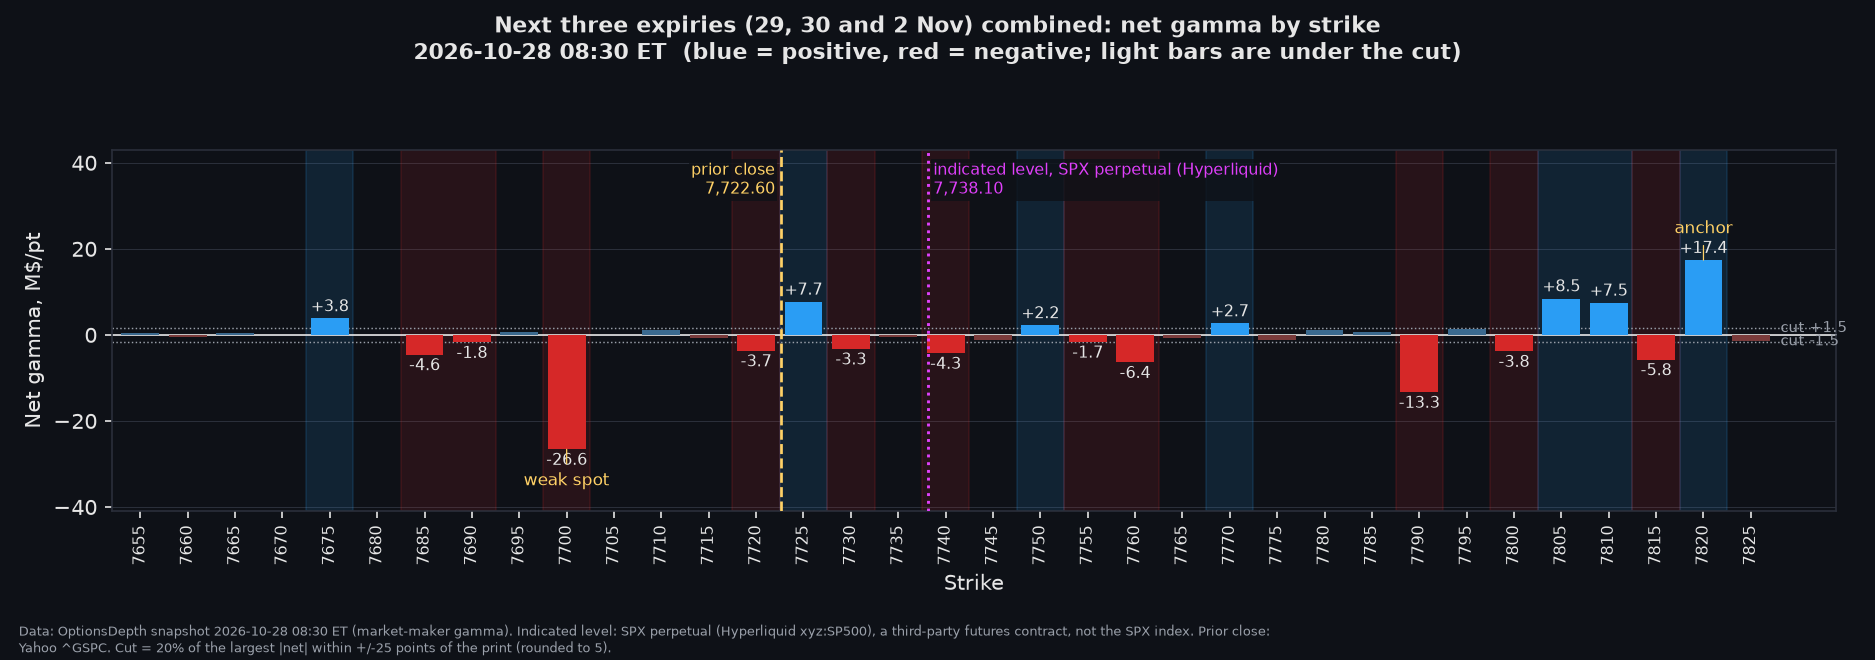
The next three expiries (29, 30 and 2 Nov)
Amplifying, net −3.0 M$/pt combined. That is higher than 3 of the last 20 sessions at this hour.
Since the 27 Oct close it went from −10.6 to −3.0 (+7.6).
Over these three expiries the anchor is 7820 (+17.4 combined: +0.4 on 29 Oct, +16.7 on 30 Oct, +0.3 on 2 Nov) and the weak spot is 7700 (−26.6 combined: −11.2 on 29 Oct, −17.7 on 30 Oct, +2.4 on 2 Nov).
Expected move to 2 Nov: ±169.6 points, a box of 7,553.0 to 7,892.2. This is a rougher rule of thumb: the one-day figure scaled by √4, the 4 sessions from the 27 Oct close to the 2 Nov close, and it assumes constant volatility.
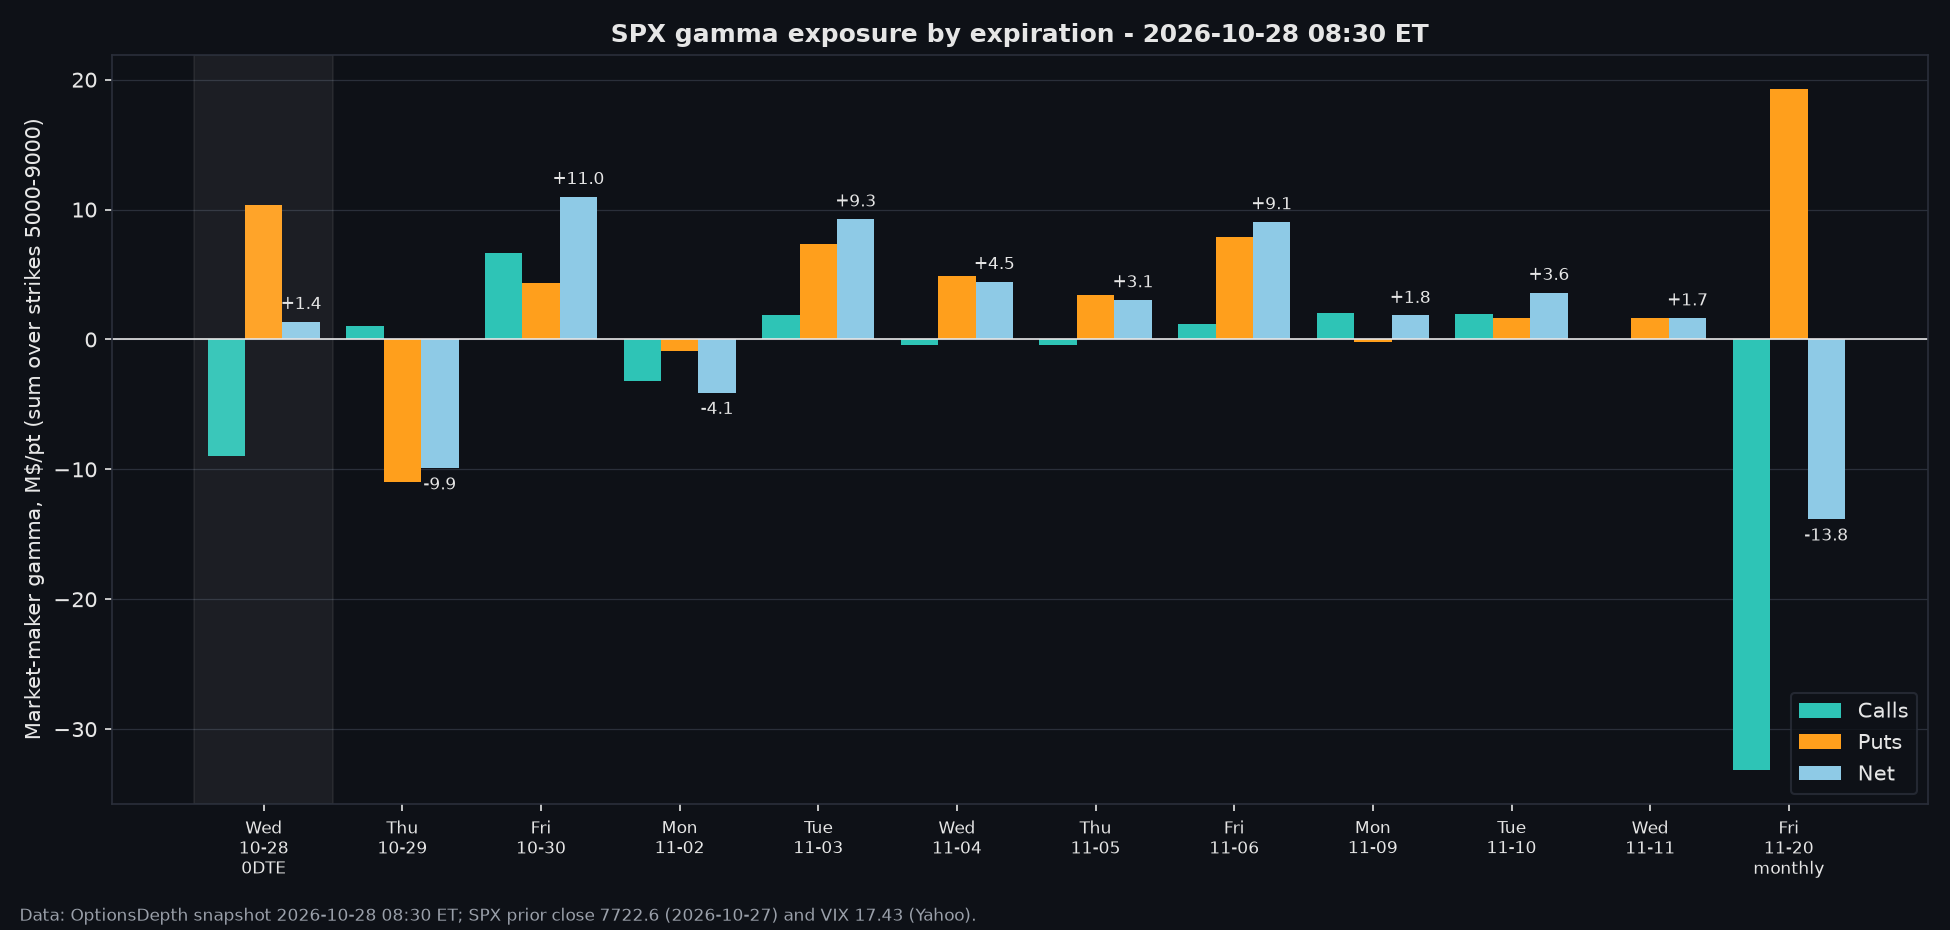
All expiries
Across all 12 pulled expiries (28 Oct to 20 Nov) the net is +17.5: steadying.
Net Drift
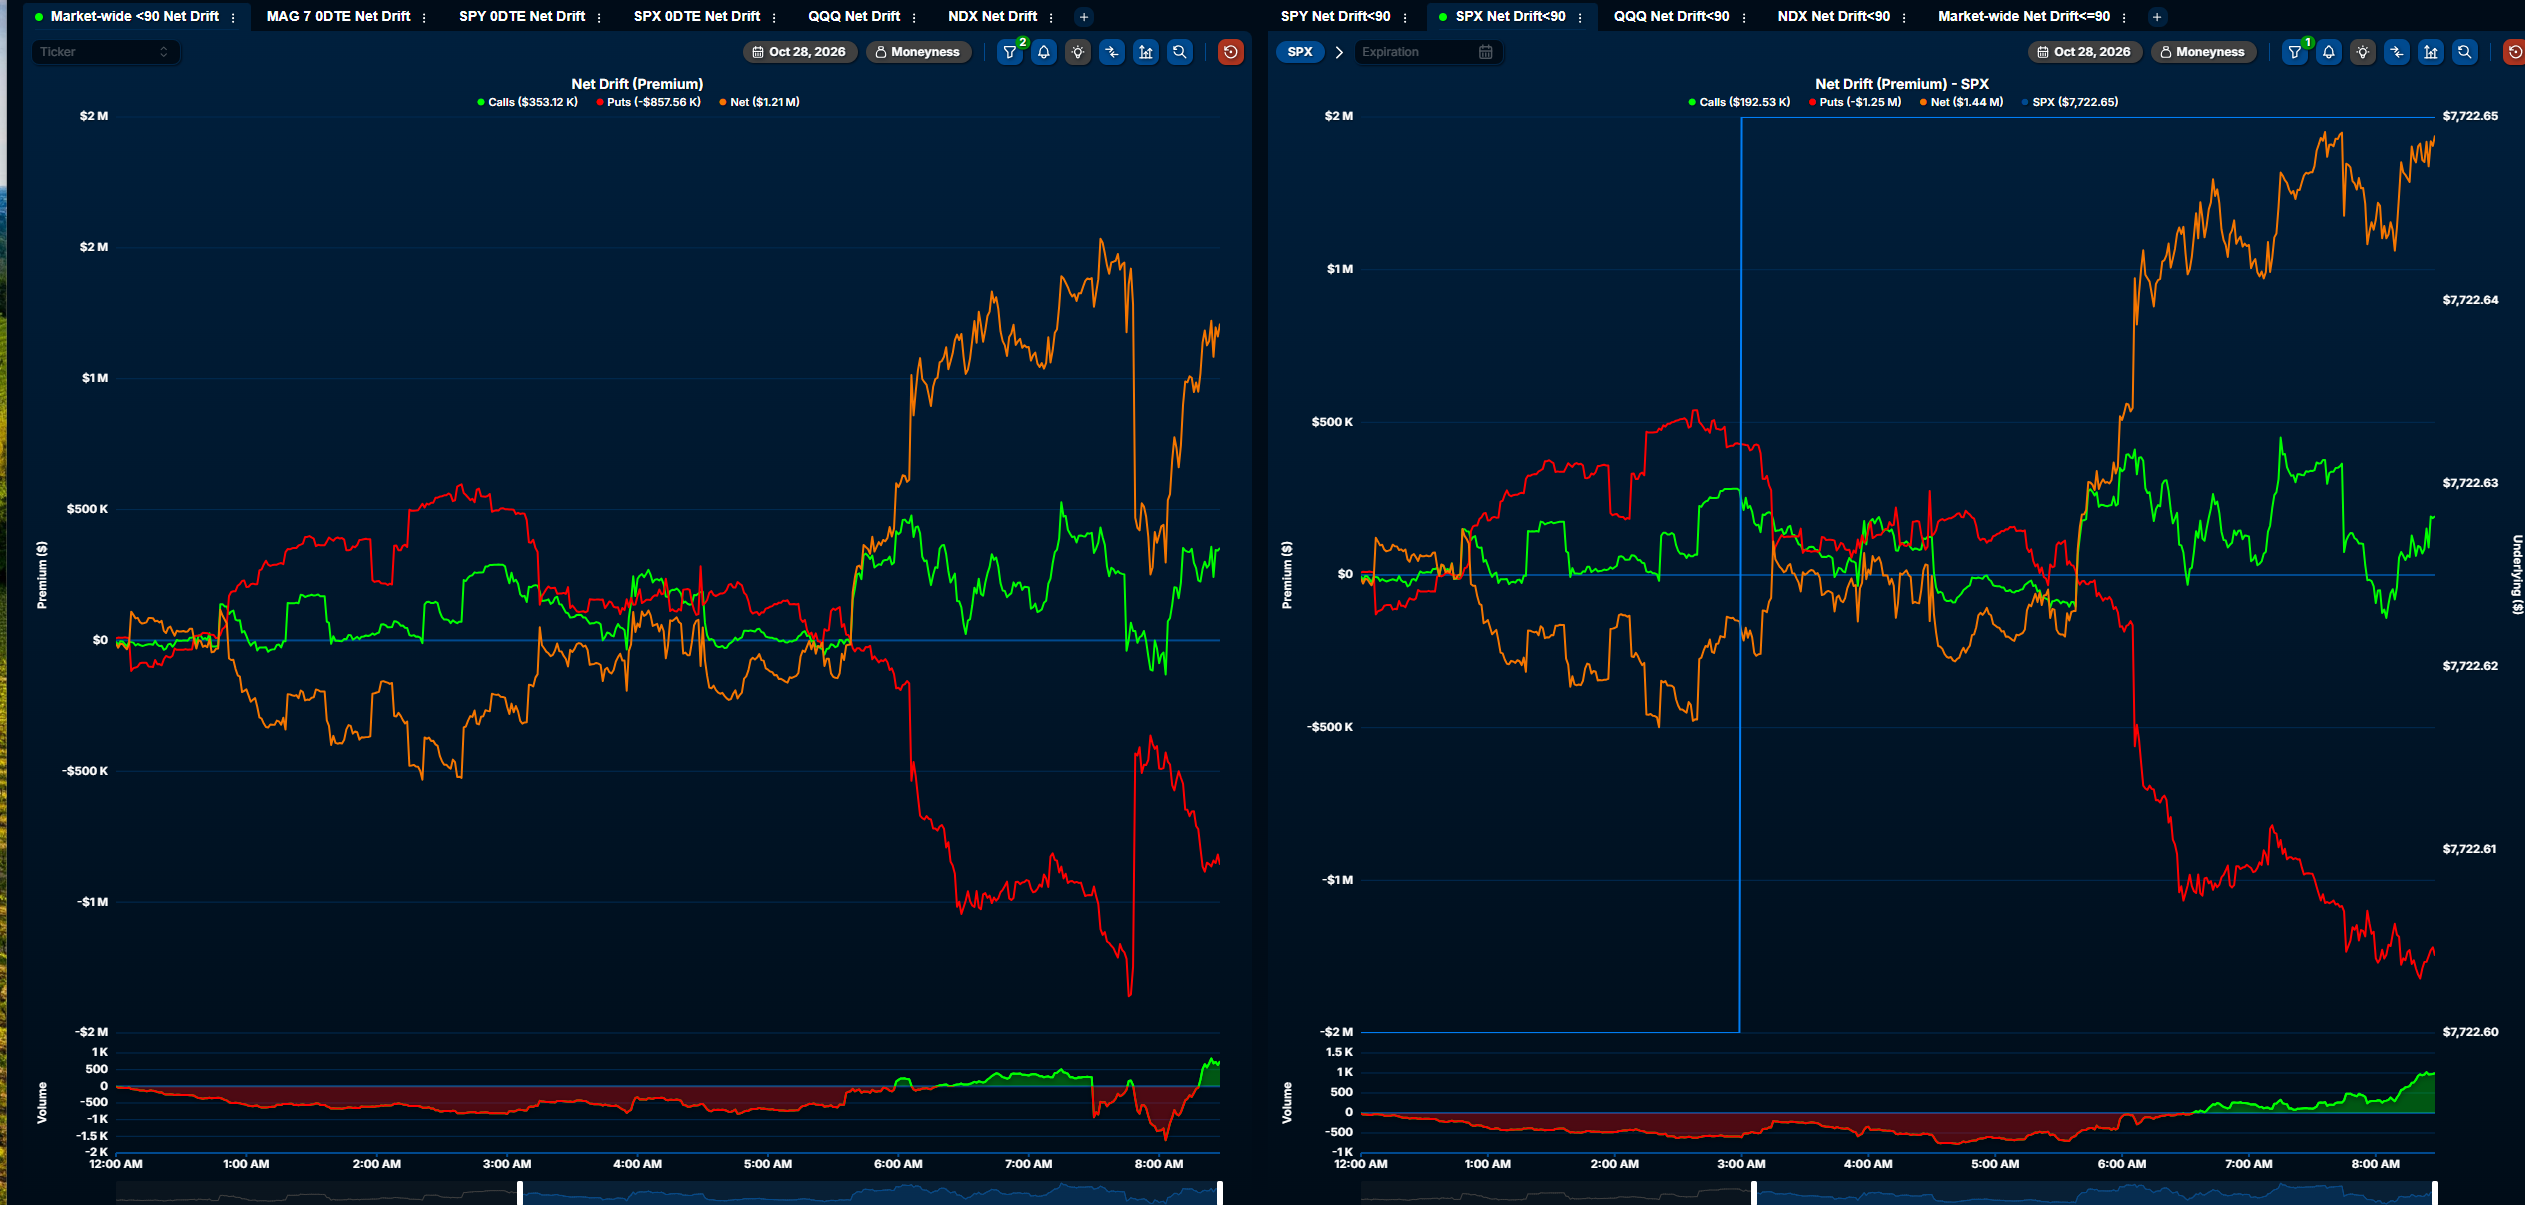
QuantData Net Drift (net customer flows, in premium) panels, covering options expiring within the next 90 days. Left: market-wide positioning. Right: SPX positioning. Green is calls, red is puts and orange is the net. Captured 28 Oct, 08:28 ET.
Sources: options positioning from OptionsDepth (snapshot 2026-10-28 08:30 ET, market-maker perspective; history at the same time of day on the previous 20 sessions and the 27 Oct 15:59 ET snapshot); prior close and VIX from Yahoo (^GSPC 27 Oct; ^VIX 1m bar 08:16 ET); indicated level from the Hyperliquid xyz:SP500 perpetual (1m candle 08:29 ET), a third-party futures contract and not the SPX index. The 20 Nov monthly expiry does not separate SPX from SPXW.
Educational only.
Copyright: Robert P. Balan (c)